Realty Executives Midwest
Ask around and almost every homebuyer out there wants to know if there’s a way to get a better deal. And just about every seller wants to know if they’ll still get top dollar.
The interesting thing is… both can be right at the exact same time. It just depends on where you live.
That’s because today’s housing market isn’t moving in one direction anymore. Some markets clearly favor buyers. Others still favor sellers. But most are sitting somewhere in the middle.
And knowing which market you’re actually in can completely change the strategy you use to buy or sell (and what expectations you should have). Let’s break it down.
So how do you know which market you’re in? There’s one number that tells the story faster than anything else: the months’ supply of homes for sale. It’s the clearest signal of who’s got leverage – and what strategy you’ll need. Think of it like this.
Imagine no additional homes were listed starting today. Months’ supply tells us how long it would take to sell everything that’s currently on the market based on today’s demand.
Generally speaking, if months’ supply is:
Fewer than 4 months: Sellers usually have the advantage.
4 to 6 months: Buyers and sellers are on more equal footing.
More than 6 months: Buyers can usually negotiate for a better deal.
Right now, the National Association of Realtors (NAR) data says that number is 4.6 and that puts the overall market back in balanced territory (see graph below):
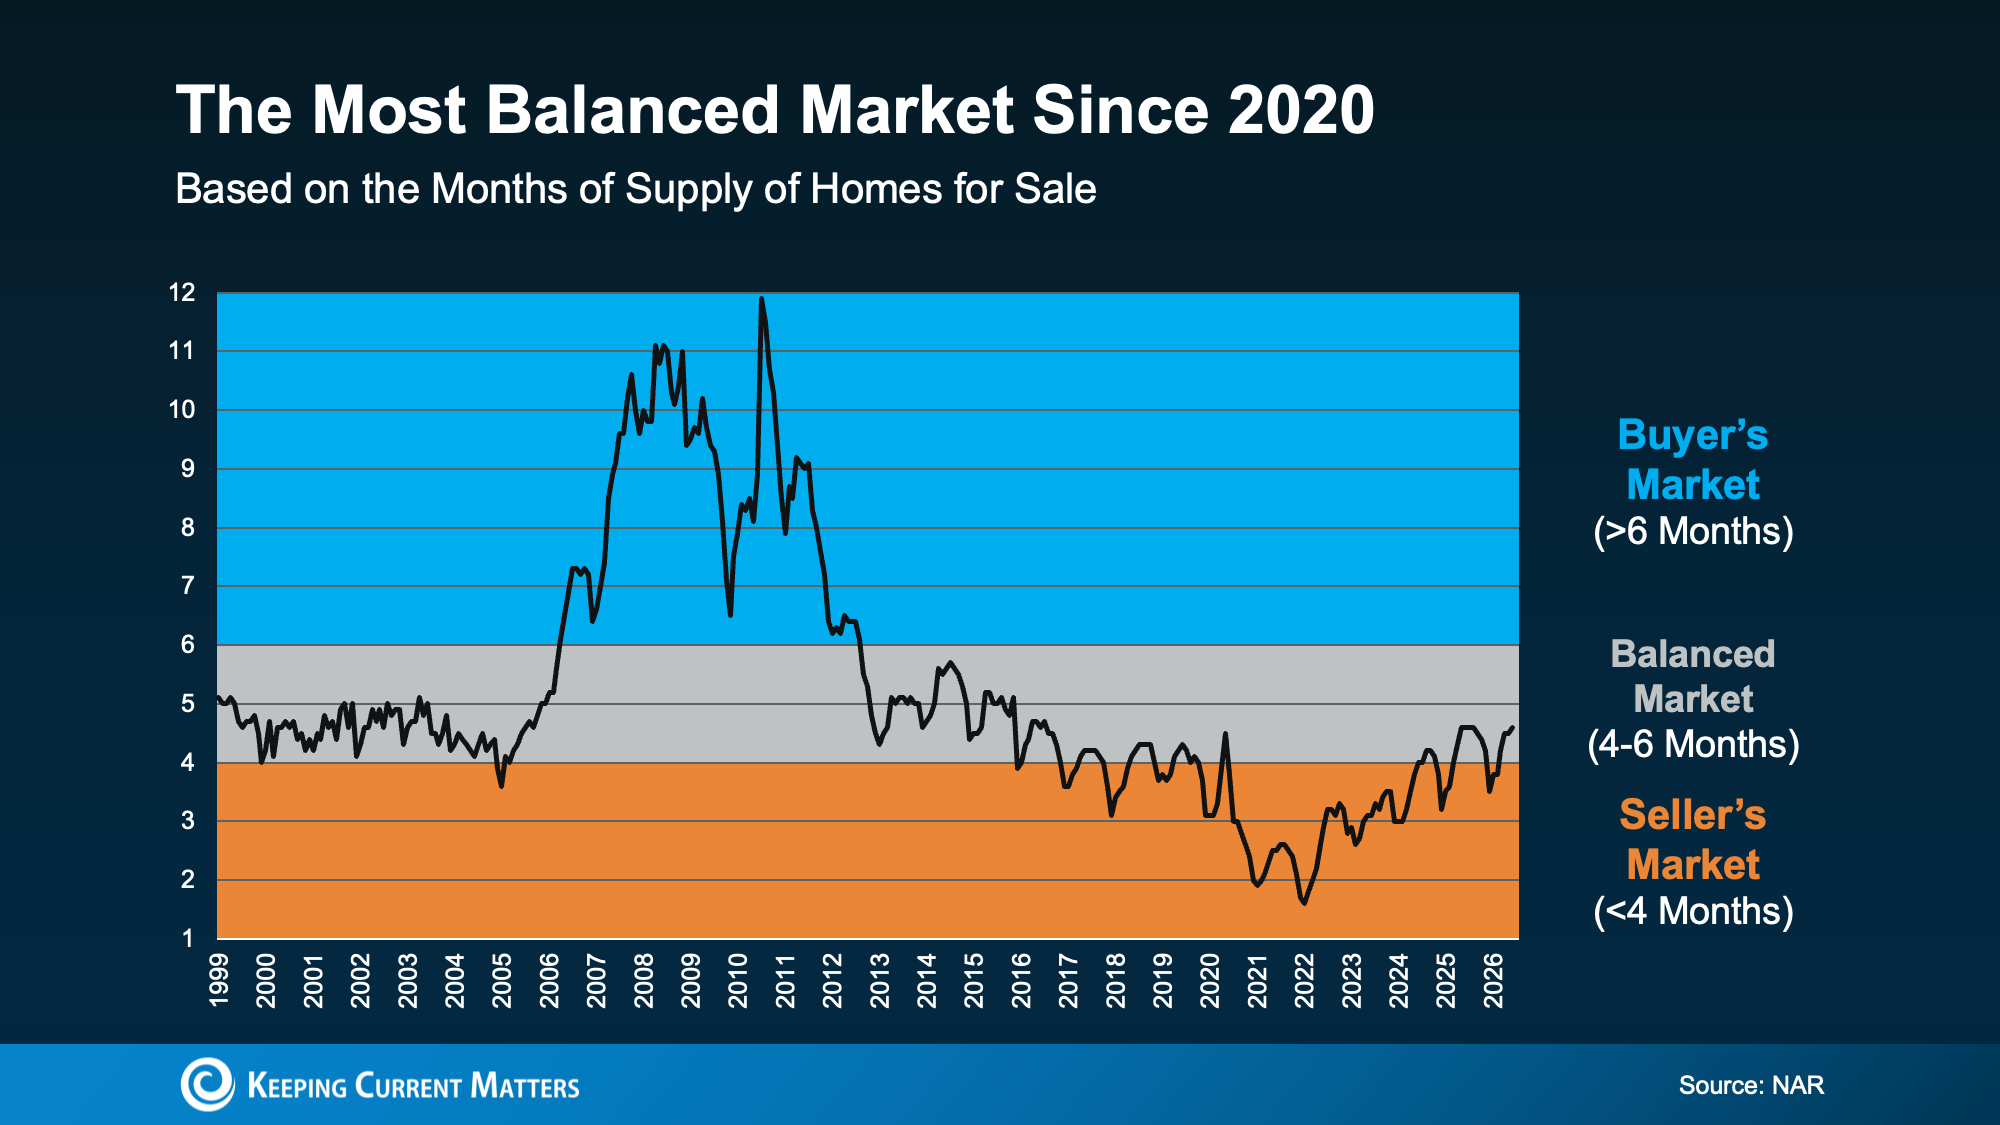
That means, as a whole, the market has finally moved back into a much more balanced range after years of being tilted in sellers’ favor. While that may look like the scales have tipped only slightly, it’s enough to make a real difference in what strategy you’ll need for your move – at least in most places.
Redfin data helps shed some light on how this shakes out across the country. It breaks down which cities are leaning in either direction (see graph below).
Some markets give buyers more leverage. Those are in blue.
Some still favor sellers. That’s the orange.
Others fall somewhere in between. Those are gray.
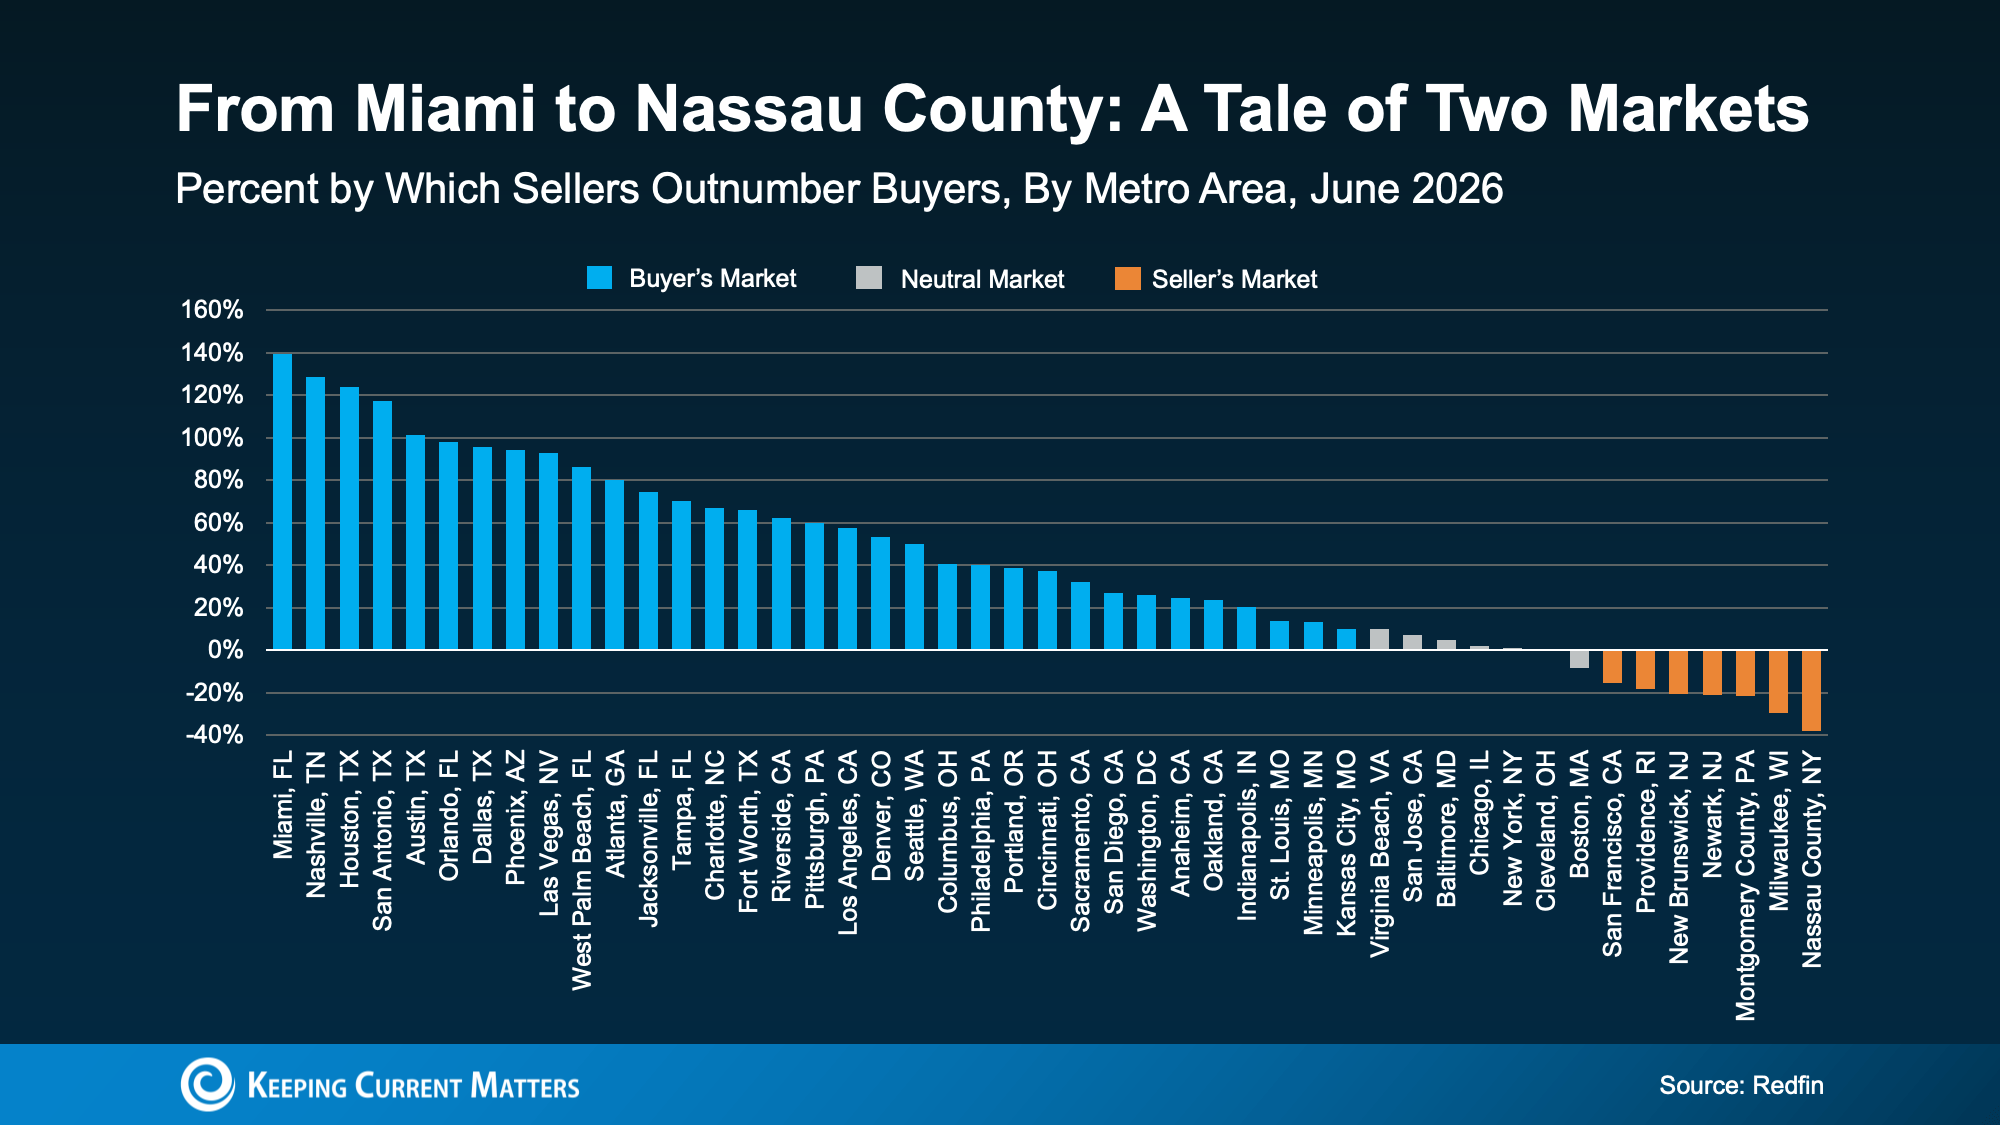 Notice anything? A lot more places are seeing more buyer-friendly conditions right now. In fact, this is the most buyer-friendly market we’ve seen in nearly 6 years.
But don’t take that as buyers have the upper hand everywhere.
There are still cities where sellers still have the power. And if you’re in one of them, your approach to selling or buying looks completely different than it would in a buyer-leaning market.
That’s why the biggest mistake isn’t thinking it’s finally a buyer’s market. And it isn’t thinking it’s still a seller’s market either. It’s making any assumption without talking to an expert agent first.
Today’s market is incredibly local. In one market, a buyer may be getting thousands of dollars in concessions from a seller. And a homeowner may have to consider dropping their price.
But in another, a buyer may be stressed about coming in with their best offer, or they may lose out on the home to another buyer. And a seller may still be seeing strong demand and prices inching higher.
Same overall housing market.
Very different experiences.
The truth is what’s happening in your back yard affects everything from pricing your house to making an offer to negotiating repairs or concessions. And that’s why an agent’s local knowledge matters more now than ever before.
Your plan has to be based on your neighborhood – and only an agent has the expertise to get that right.
This market isn’t one-size-fits-all.
If you're wondering who has the upper hand where you live, talk to a local agent. They’ll help you understand what's happening in your market, who's got the leverage, and what strategy gives you the best shot at getting what you want.
Source: Keeping Current Matters
Realty Executives Midwest
1310 Plainfield Rd. Ste 2 | Darien, IL 60561
Office: 630-969-8880
E-Mail: experts@realtyexecutives.com
If you’re a homeowner getting ready to move, one question usually comes first: should you buy your next home before you sell, or sell your current house before you start looking?
There’s no single right answer. The best call depends on your finances, your local market, and your timeline. And a trusted agent can help you weigh all of it.
But in a lot of cases these days, selling first puts you in the stronger spot.
Selling is usually the trickier half of a move today, so getting it done first clears your biggest hurdle. And that’s especially true right now, because there are more homes for sale than there are buyers, which means houses are taking longer to sell than they did a year or two ago.
So how does leading with your sale pay off? Let’s start with the money.
Buy before you sell, and you could end up carrying two mortgages at once. And especially since houses are staying on the market longer these days, that overlap may drag on for more time than you’d planned. And if unexpected repairs come up, it could get even more expensive.
Selling first takes that risk off the table, so you’re not multitasking homeownership. As Ramsey Solutions puts it:
“It’s best to sell your old home before buying a new one to avoid unnecessary risks and possible headaches.“
This is always true, but one of the biggest perks of selling first is that you’ll know exactly how much money you’re walking away with. And one of the big figures that matters in that conversation is how much equity you have in your current place.
Equity is basically your house’s value minus what you still owe on your mortgage. And it adds up fast. According to Realtor.com, homeowners who’ve been in their home for 5 years have about $180,000 in equity on average. And those who’ve had their home for 6-10 years? They have over $340,000.
After you sell, you can use that money to cover your down payment or even buy your next home in cash. And knowing that profit up front helps you plan your next move.
When your house is already sold, you don’t have to make your offer contingent on that sale. In a market where buyers are taking their time, that’s exactly what a seller wants to see.
Picture it from the seller’s side. If their house has been sitting for a while, they’ll gravitate toward the offer most likely to close without a snag.
That can also give you room to ask for a little more, like repairs, since a motivated seller would rather keep things moving than lose you and wait for another offer to come in. Your agent can help you make the most of your upper hand in that scenario.
Selling first has its tradeoffs too, and it helps to see the pros and cons side by side before you decide. Here’s a quick breakdown based on information from Zillow (see visual below):
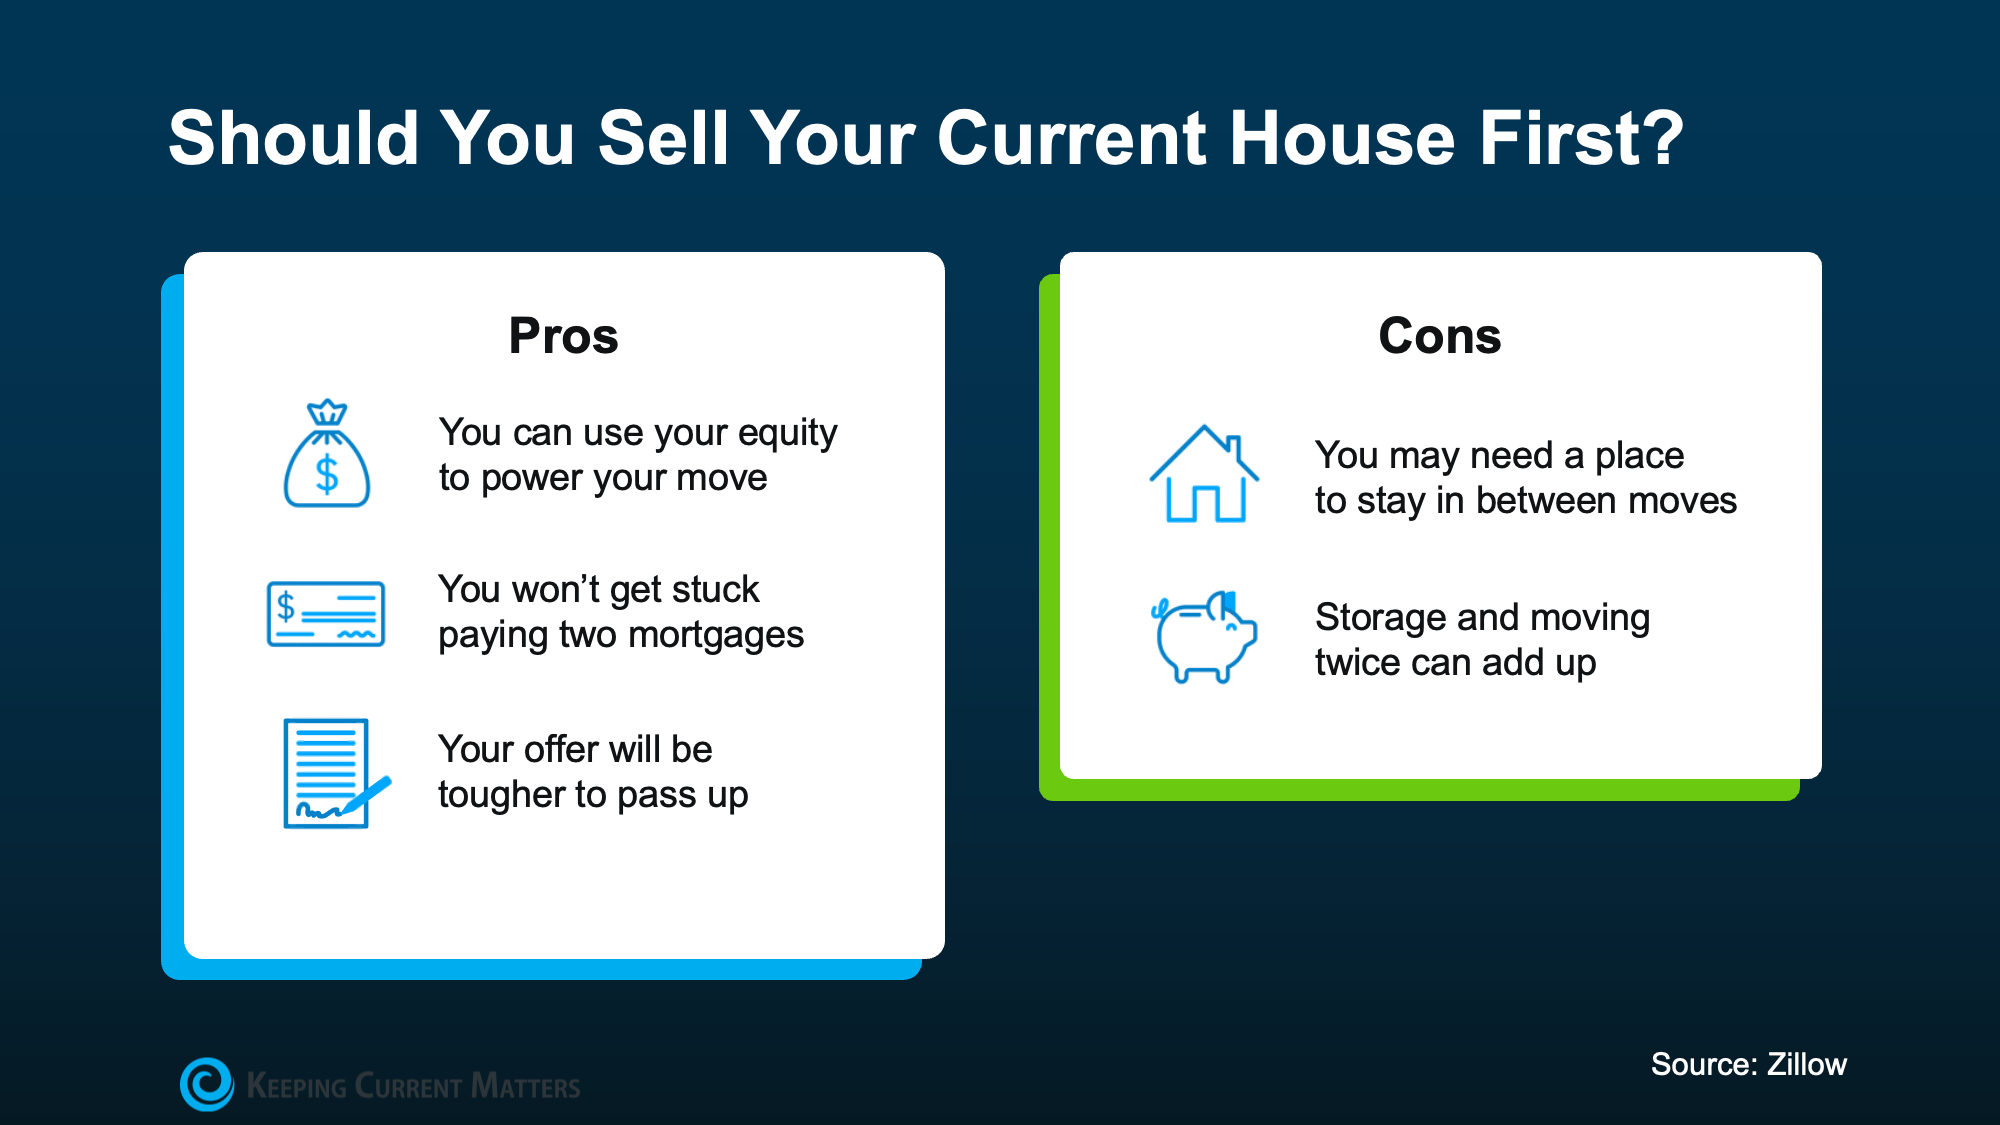
The cons are manageable with the right plan, so talk about them with your agent. They can help you negotiate things like a rent-back, where you stay in your house for a set time after closing, or line up flexible closing dates to keep the transition smooth.
There's no one-size-fits-all answer to buying and selling at once. But for a lot of homeowners, leading with the sale makes moving easier on their mind and their wallet.
Connect with a local agent, and they’ll help you navigate selling and buying with more confidence, more financial power, and less stress.
Source: Keeping Current Matters
Realty Executives Midwest
1310 Plainfield Rd. Ste 2 | Darien, IL 60561
Office: 630-969-8880
E-Mail: experts@realtyexecutives.com
If you’ve thought about buying a home in the past few years, you may have run into two frustrations: asking prices that kept climbing and too few homes to choose from.
In many places, both sticking points are letting up this summer, with lower asking prices and more homes for sale. Let’s look at the trends, and what they mean for your search.
According to Realtor.com, the national median asking price was $430,000 in June, nearly $11,000 under what it was the year before (see graph below):
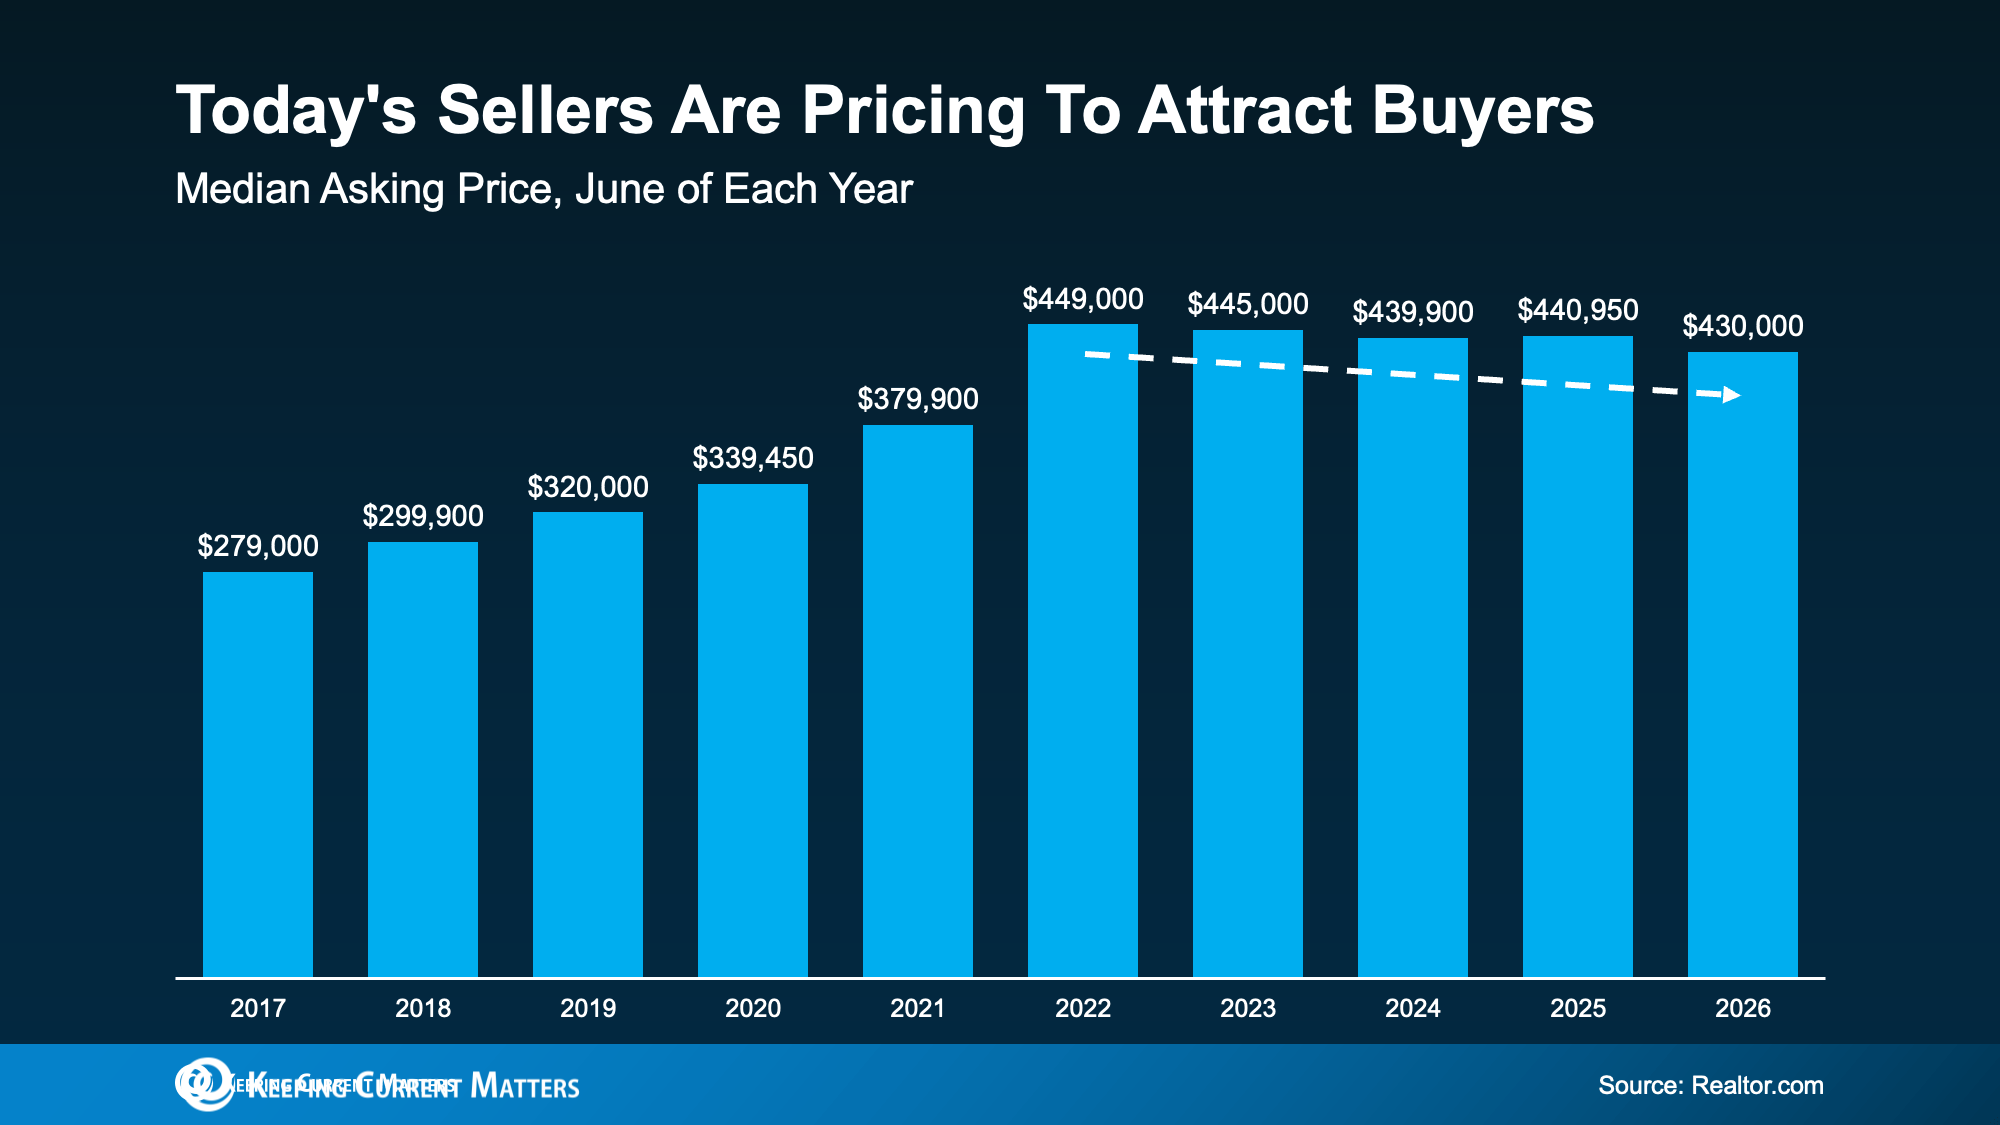
That’s the eighth month in a row that the typical asking price has dipped below where they were the previous year, according to the same Realtor.com report.
And while falling prices can sound worrying, this isn’t a sign of an impending crash. We’re talking about asking prices, not sold prices. This is a sign that today’s sellers are meeting the market where it is and pricing to draw buyers. And that’s actually something normal we’d expect from the market. As Danielle Hale, Chief Economist at Realtor.com, puts it:
“Sellers are reading market conditions and are pricing accordingly from the start rather than listing high and cutting later, and buyers are taking note and making bids. This is a welcome sign that we are in a functioning market.”
Asking prices were never going to climb forever – now they’re just settling closer to what buyers can actually pay. That signals a healthier market, and sellers re-adjusting their expectations.
If you’ve spent the past few years watching homes disappear before you could even schedule a tour, this is for you.
Supply is starting to catch up. According to Realtor.com, the number of homes listed for sale in June was the highest June number we’ve seen in three years (see graph below):
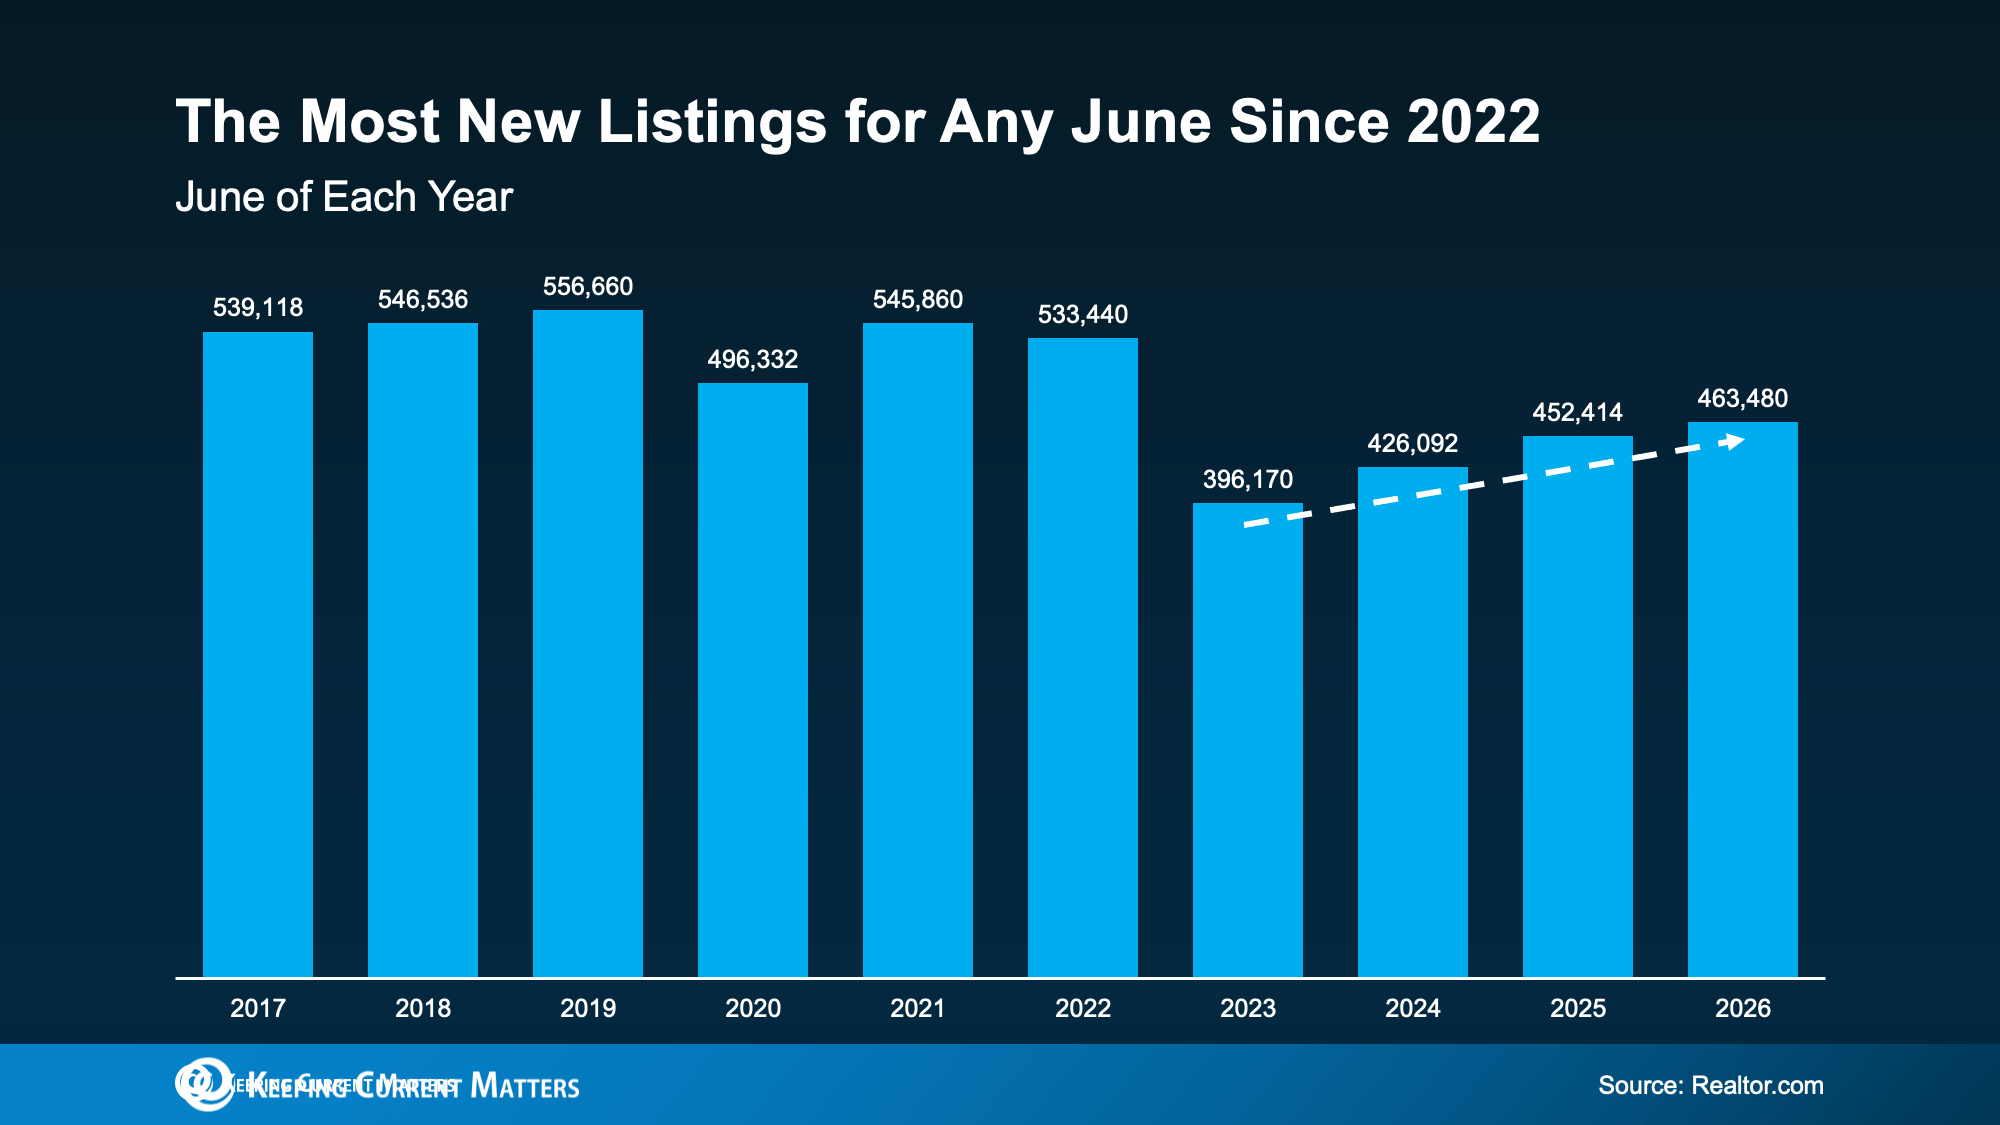
This means more options for you and less competition for each one.
Now, supply is not back to normal everywhere. As you can see, we’re still down from where we were back in 2017-2019. But in many places, it’s better than it’s been in a while. Here’s how that helps you.
You don’t have to rush an offer just to stay in the running, and you have better odds of finding and landing the right home, not just the one that’s available. Plus, you’ll have more room to negotiate, so you’re searching from a stronger position than buyers had even a year ago.
For first-time buyers looking for lower-priced homes, these trends line up especially well. Mischa Fisher, Chief Economist at Zillow, explains:
“The lowest price tiers are exhibiting some softness in terms of price, they also had the most listing-activity growth, the first time since 2022 that’s been the case.”
So, if you’re searching for your first place or your next house, there’s a little more to choose from and a little more give on price.
If a tight budget or a thin selection has kept you from buying a home, now might be the time to restart your search.
Source: Keeping Current Matters
Realty Executives Midwest
1310 Plainfield Rd. Ste 2 | Darien, IL 60561
Office: 630-969-8880
E-Mail: experts@realtyexecutives.com
If the first half of this year has left you feeling stuck, you’re not the only one. Mortgage rates stayed higher than people wanted. Affordability remained tight. And uncertainty overseas added another layer of pressure nobody saw coming.
That’s why so many people are asking the same question: Will the second half of the year be any better for the housing market?
While nobody has a crystal ball, there are a few encouraging signs things could start moving in a better direction. Here’s what to watch.
One of the biggest reasons mortgage rates haven’t come down yet is inflation. And higher energy prices and uncertainty overseas are at least part of the reason inflation is still elevated. The encouraging news?
Oil prices have already started coming back down.
That may not sound like it has much to do with buying a home. But historically, mortgage rates and oil prices tend to move in the same direction.
Take a look at the graph below. Generally, they rise and fall together. Both went up in February when the conflict began. While there’s been some volatility lately, experts at the U.S. Energy Information Administration (EIA) say oil prices are forecast to come down. And since oil prices have been on an overall downward trend lately, mortgage rates could come down too:
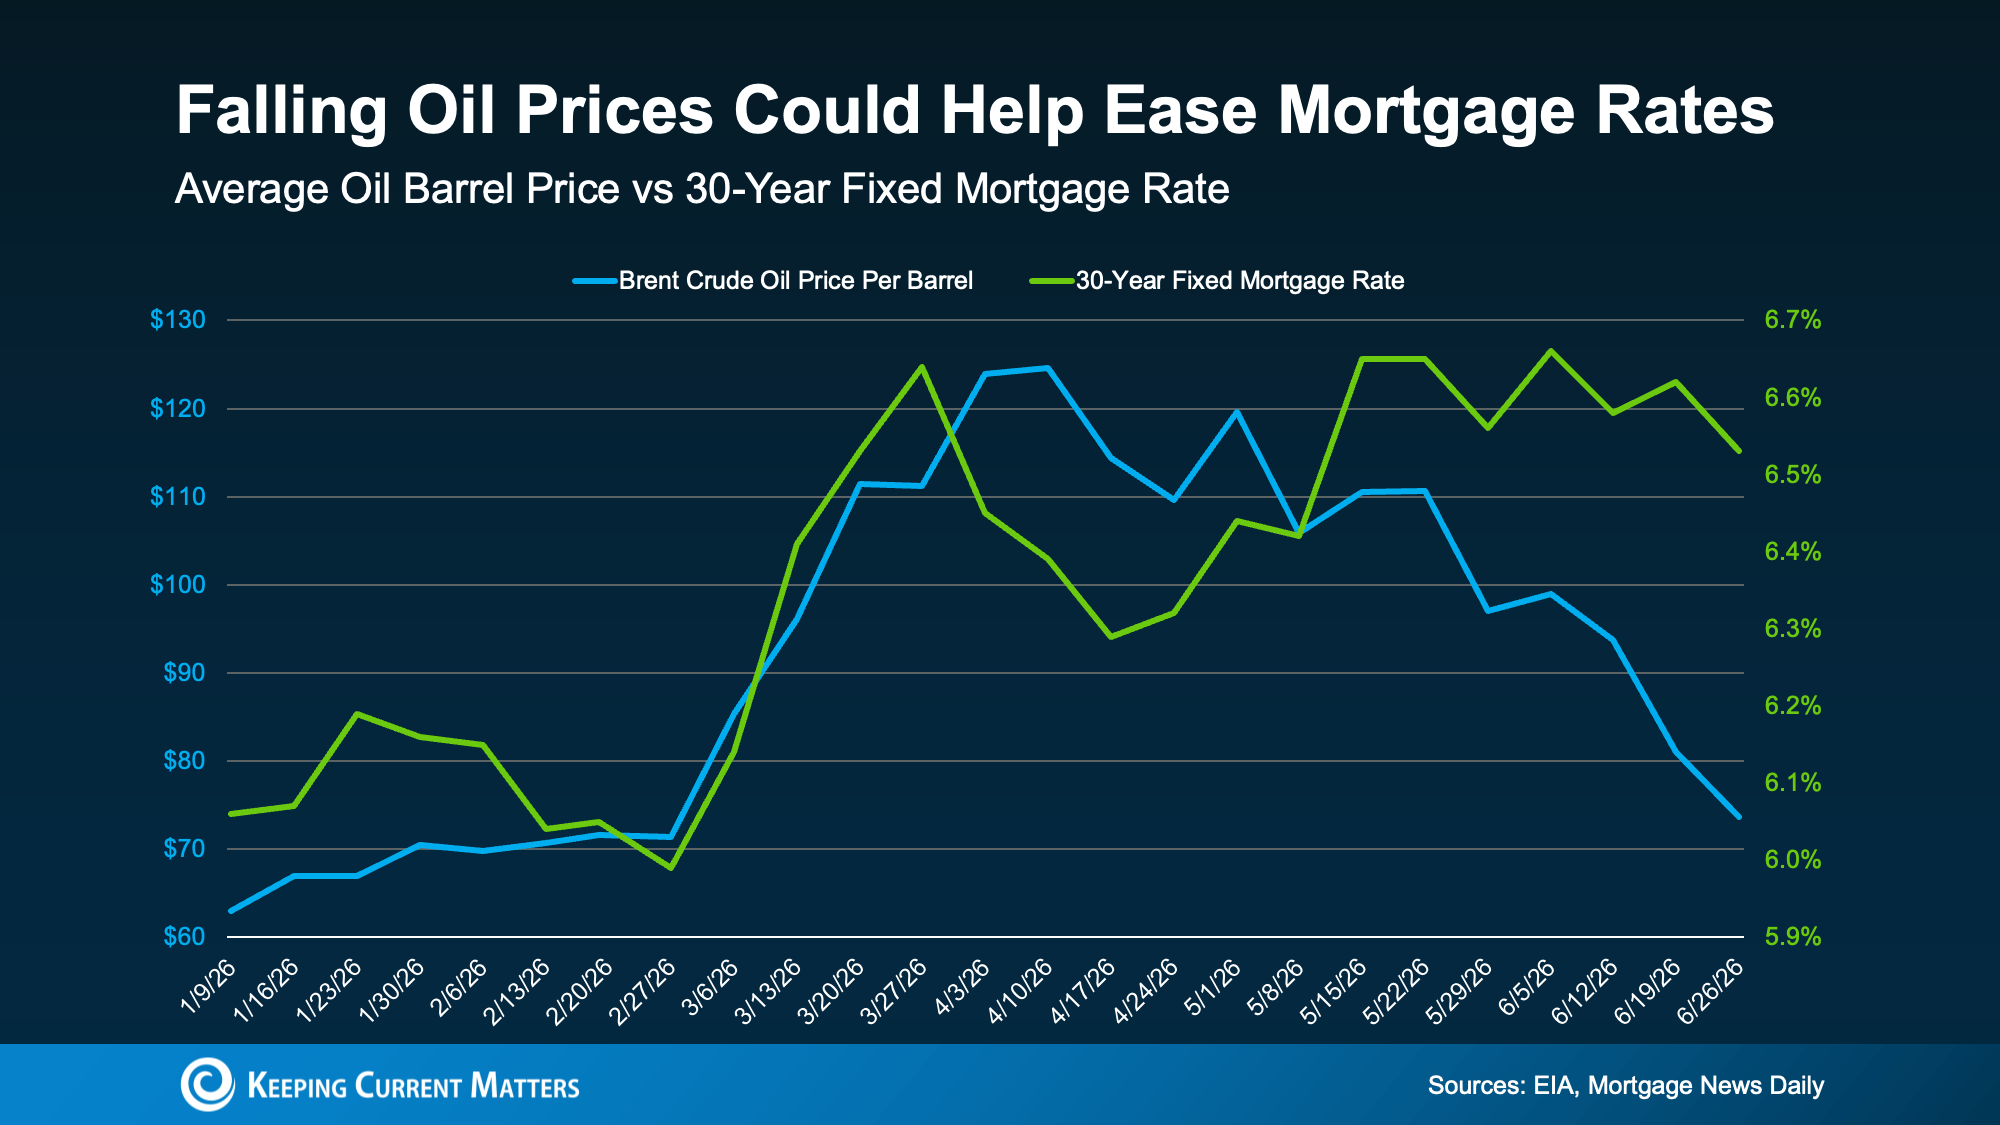
It’s too soon to say exactly when that will happen (or by how much they’ll fall), but if energy prices go down, inflation cools off, and tensions overseas ease, mortgage rates could come down in the second half of the year.
And that’s good news for anyone thinking about moving. The first half of the year tested everyone’s patience. The second half may finally reward it.
A lot of people want home prices to fall too. But that’s not what most forecasts show.
While price trends are going to vary by area, and some places are seeing mild declines, experts still expect home prices to net positive this year at the national level.
In fact, they’re projecting prices will rise by an average of 2.3% in 2026 (see graph below):
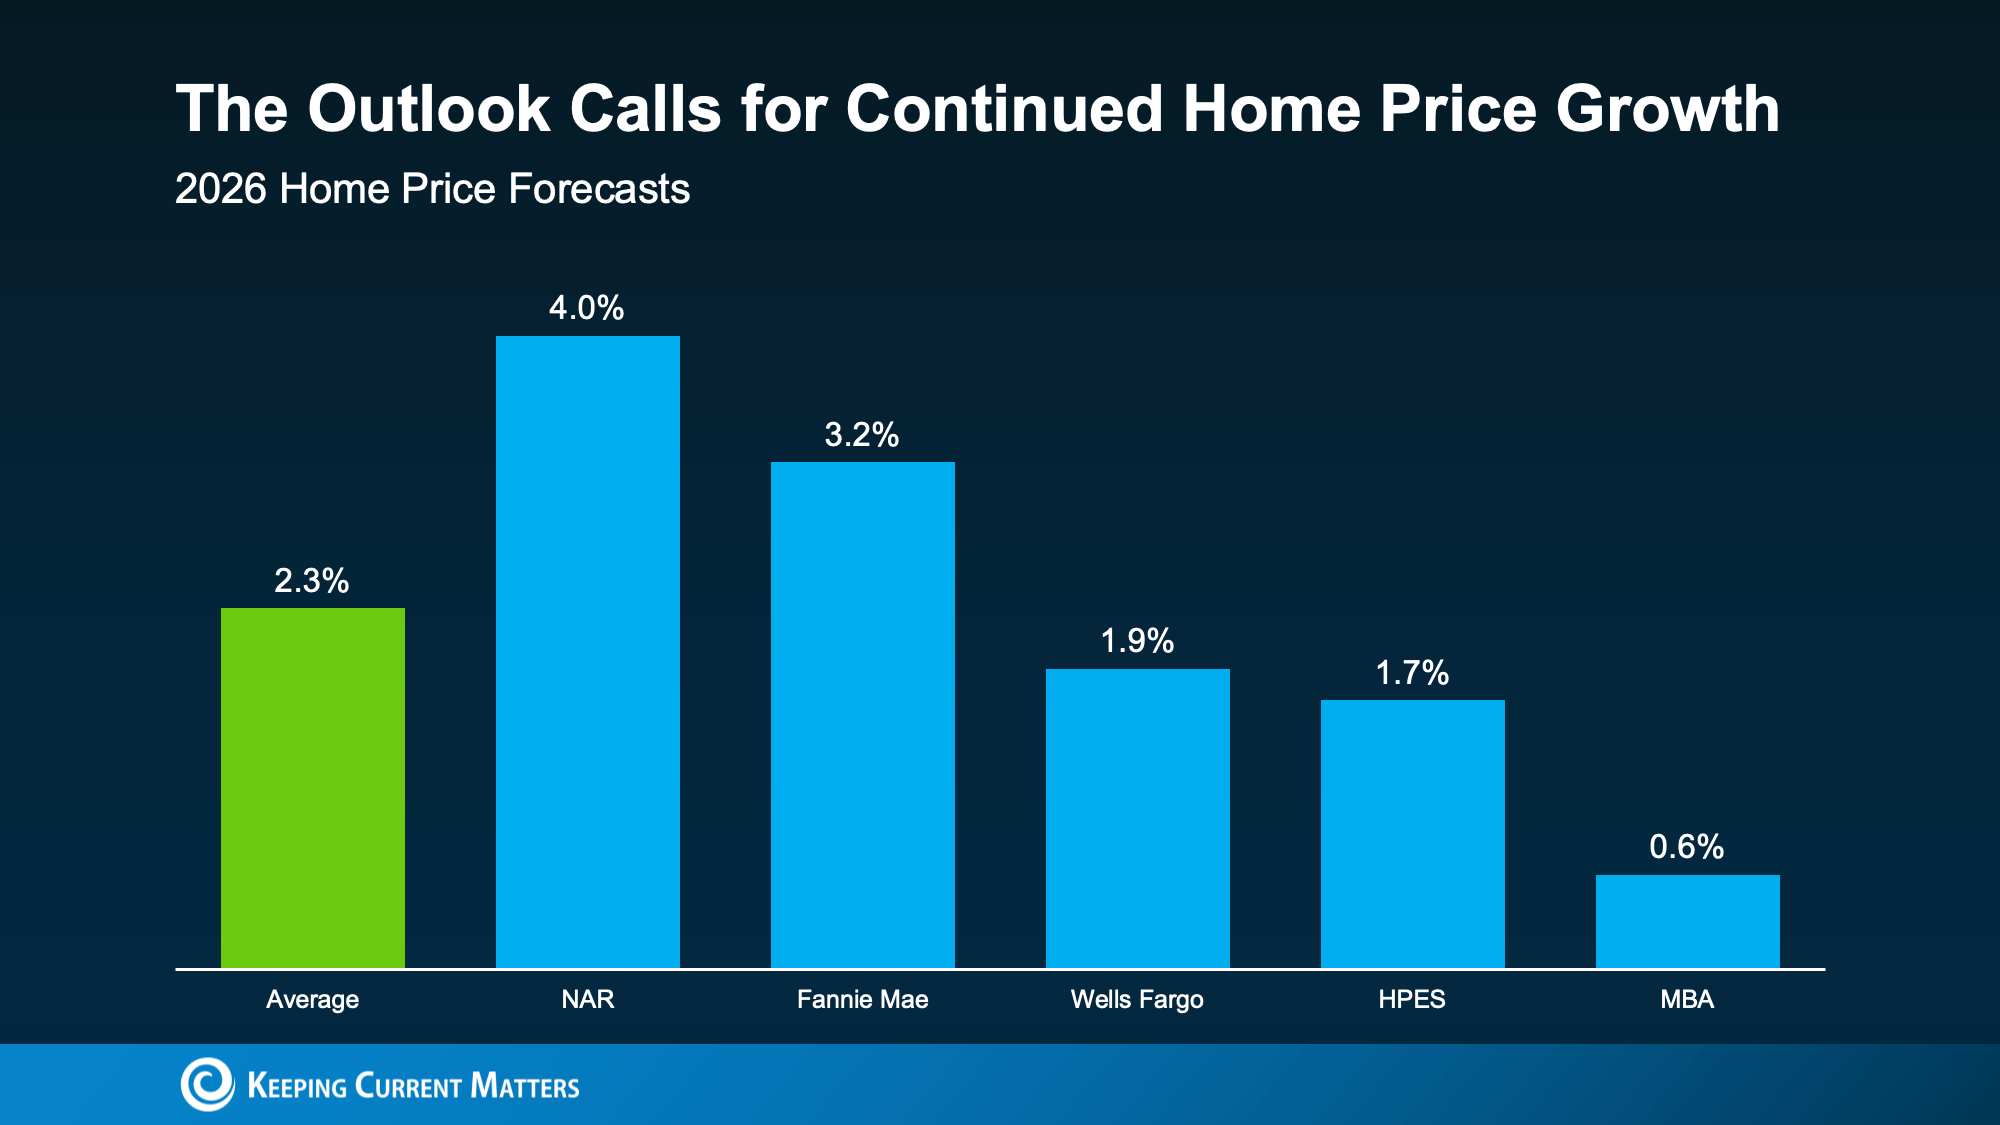
What does that mean for you? Right now, Federal Housing Finance Agency (FHFA)data shows prices are up about 1.7% nationally year-over-year. The average forecast for all of 2026? 2.3%.
Based on those projections, home price growth would have to pick up a bit during the second half of the year. Nothing dramatic, just enough to finish the year around that projected 2.3% gain.
Here’s why that’s possible.
The number of homes for sale has grown, but that growth may be starting to slow down. And if rates improve, more buyers could jump back into the market. More buyers competing could put modest upward pressure on prices, especially if inventory’s not growing as fast.
That’s why buyers shouldn’t assume waiting will guarantee a lower price later. And for sellers, that’s great news if you’ve been worried about your home’s value.
If you’ve been wondering why the housing market has felt quieter lately, you’re not imagining it. Home sales have been slower than many experts expected. But that doesn’t mean people have stopped wanting to move.
A lot of people still want or need to make a change. They’ve just been waiting for more certainty, better affordability, or a clearer read on where the market is headed. And early signs show that may be on the horizon.
If rates ease and confidence improves, more people may finally move. As Odeta Kushi, Deputy Chief Economist at First American, explains:
“Overall, we expect pent-up demand to continue emerging gradually. But the pace of recovery will vary significantly across markets and will depend on the path of rates, labor market conditions and inventory growth.”
Based on the latest forecasts, to hit the number of sales expected this year, here’s what would have to happen. The second half of the year would need to outperform the first in sales (see graph below):
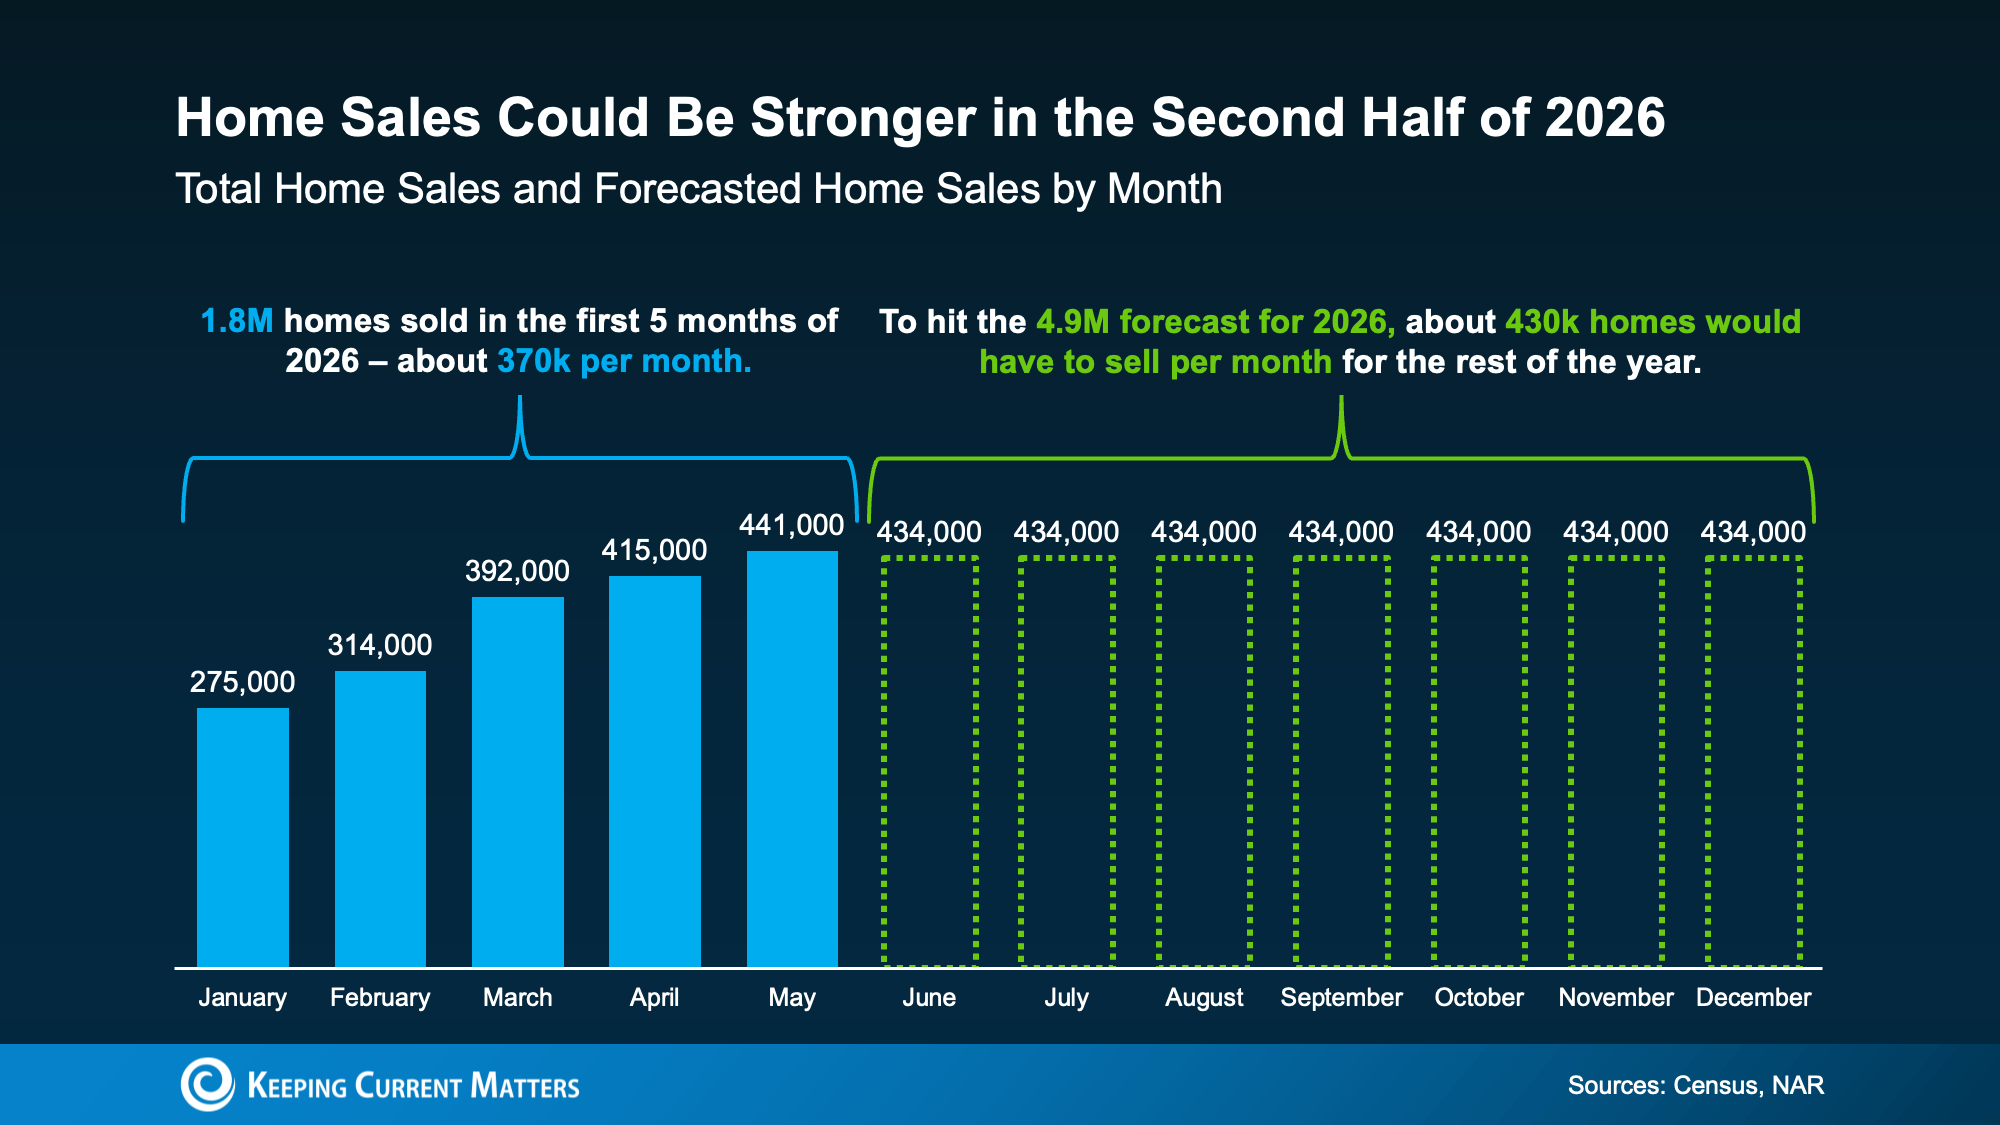
In fact, each month for the rest of 2026 would have to come close to matching the best month we’ve had so far this year (May). That’s a sign the experts are calling for more momentum headed into the second half.
More people will finally make their move happen – and you’ve got the chance to be one of them.
The second half of the year probably won't be perfect. But it could be better.
Mortgage rates may ease. Home sales could pick up. And prices are expected to continue rising at a healthier, more sustainable pace. If you've been waiting for signs of progress, this is it.
If you want to understand what these forecasts mean for your plans and what’s happening in your local market, connect with an agent.
Source: Keeping Current Matters
Realty Executives Midwest
1310 Plainfield Rd. Ste 2 | Darien, IL 60561
Office: 630-969-8880
E-Mail: experts@realtyexecutives.com
Open up a home search and you’ll see them. Listings that have been on the market for two months. Three. Some longer.
Most buyers scroll right past them, assuming something’s wrong with the house. But that instinct could be costing you, since the longer a home sits, the more motivated the seller usually gets.
If affordability has been your #1 hurdle to buying, here’s a surprisingly simple strategy that could help you finally get your foot in the door. Start with the homes that have been sitting the longest. That’s often where the best deals are.
Here’s why. Data from Realtor.com shows there’s a connection between longer time on the market and lower sales prices. Basically, the longer a house sits, the more likely it is that the seller will reduce the price (see graph below):
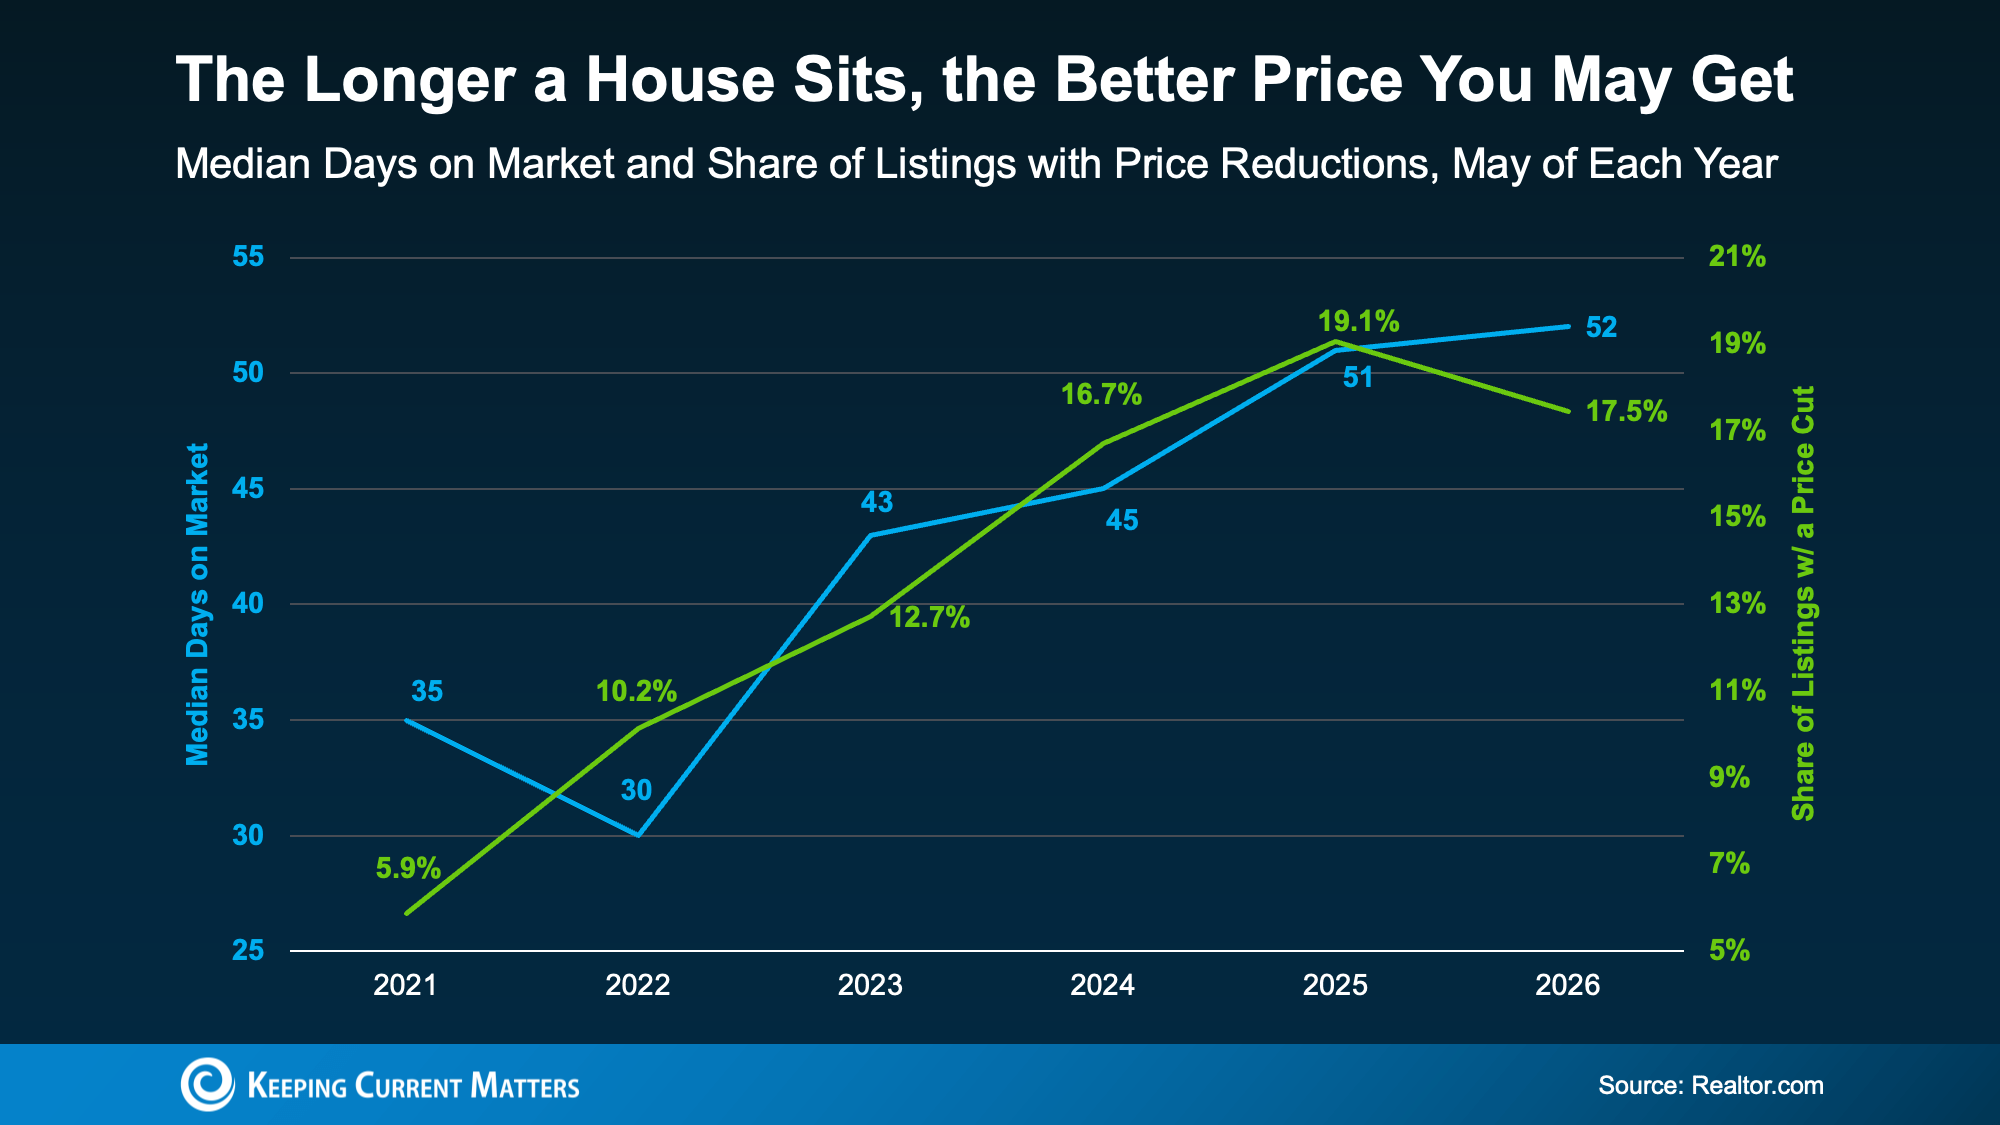
The blue line tracks how long homes stay on the market, while the green line tracks the share of homes getting a price reduction. As one climbs, so does the other.
And if you focus on these homes that are just sitting and waiting, the opportunity for you is bigger than you may think right now.
Redfin data shows there’s $347 billion worth of stale listings on the market right now – more than ever before for this time of year. So, ask your agent to filter listings for you from oldest to newest. The home that fits your budget might already be there. Just further down the list than you thought.
Let’s say you do that and something catches your eye. Still, you might be questioning why the home has been sitting in the first place. Just remember, sometimes it has nothing to do with the home itself.
According to Redfin, common causes are:
The asking price was set too high to start
The home didn’t show well online
There are a lot of homes for sale in the area, so it just got buried
So, nothing that’s necessarily a dealbreaker, or even anything that’s wrong with the home itself. If there’s a real issue, a thorough inspection will surface it. And that’s information you can use to negotiate. Not a reason to assume it’s a house worth skipping over.
So how do you capitalize on a lingering listing? According to USA Today, you have two main levers to pull.
The first is price. Work with your agent to study what comparable homes recently sold for, then build an offer around that. Coming in below asking price is fair game when a home has been sitting.
The second is concessions. If a seller won’t budge much on price, they may still help in other ways, like covering some closing costs, repair credits, or even a mortgage rate buydown that lowers your monthly payment.
A local agent has the context to tell which homes are the real opportunities and which are skippable.
A house sitting on the market isn’t always a glaring red flag. In today’s market, it may be your best opportunity yet.
For help deciding which lingering listings are actually worth a second look, connect with a local real estate agent.
Source: Keeping Current Matters
Realty Executives Midwest
1310 Plainfield Rd. Ste 2 | Darien, IL 60561
Office: 630-969-8880
E-Mail: experts@realtyexecutives.com
Realty Executives agents are real estate experts. They have the education and expertise you need to navigate through the process of buying or selling a home. From listing at the right price to making the best offer, our Executives have witnessed the best - and most regrettable - decisions homeowners and homebuyers can make. Every day, they are immersed in every aspect of real estate that includes comparable home price analysis, property surveys, credit reports, open houses, HOA agreements, lenders, title companies, homeowners’ insurance, walk-throughs, terms of sale or purchase, repairs, concessions and closing documents. Let our accomplished Executives help navigate you through the process of buying or selling a home.